
Key Takeaways
- A coastal home should be evaluated for location, condition, carrying costs, maintenance needs, and daily practicality.
- Flood exposure, elevation, drainage, insurance availability, and prior water intrusion deserve early attention.
- Salt air, wind-driven rain, snow, and seasonal moisture can affect exterior materials and mechanical equipment.
- Docks, shoreline structures, private roads, wells, and septic systems may need separate review.
- Local shoreland rules can shape future renovation, landscaping, rental, and waterfront-use plans.
Buying near Frenchman Bay, on Mount Desert Island, or in nearby Hancock County communities can be an exciting move, but a view of the water is only one part of the decision. Before making an offer, buyers should look closely at weather exposure, access, building condition, ownership costs, and the rules that apply to the parcel.
For a local perspective during that process, Bar Harbor ME real estate expert Steven Shelton works through Acadia Realty Team, a real estate site focused on property searches, local market guidance, and buying and selling support across Bar Harbor, Ellsworth, Southwest Harbor, Blue Hill, Mount Desert Island, and nearby coastal areas. That local focus is valuable when a buyer needs to assess more than listing photos, particularly for waterfront homes, land, and properties with seasonal considerations.
Why Coastal Homes Need a Closer Review
Coastal Maine homes live with conditions that inland properties may experience less often. Salt air, strong winds, fog, heavy rain, freeze-thaw cycles, snow, and prolonged moisture exposure can place additional demands on roofs, siding, decks, windows, drainage systems, and outdoor equipment. A house that appears well-maintained during a sunny showing may still have issues that only become apparent in a detailed inspection.
Two similarly priced homes can have very different long-term costs. One may have a newer roof, sound drainage, accessible year-round roads, and manageable insurance. The other may need exterior work, have a difficult driveway, face higher coverage costs, or include aging shoreline improvements. Evaluate the overall ownership picture rather than treating the asking price as the sole basis for comparison.
Start With the Exact Location
The town name matters, but the individual site matters just as much. A home a short distance from the shoreline can feel and function very differently from one directly exposed to a bay, harbor, tidal inlet, pond, or wetland. Walk the property at different times if possible, and consider how it will work in summer traffic, winter weather, and heavy rain.
- Note the distance from saltwater, freshwater, wetlands, and tidal areas.
- Look at elevation, slope, drainage swales, low spots, and the direction of prevailing exposure.
- Drive the route to grocery stores, health care, schools, marinas, trails, and village services.
- Consider road width, parking, plowing, privacy, traffic, and emergency access.
- Ask whether the property is practical for year-round living, remote work, guests, or a second-home routine.
Shoreland requirements may limit future changes. Maine’s shoreland zoning guidelines explain that regulated areas can include land within 250 feet of tidal waters, coastal wetlands, certain water bodies, and defined freshwater wetlands, with separate rules applying near certain streams. Municipal ordinances can be more restrictive, so buyers should confirm details with the local code enforcement office.
Check Flood Exposure and Drainage
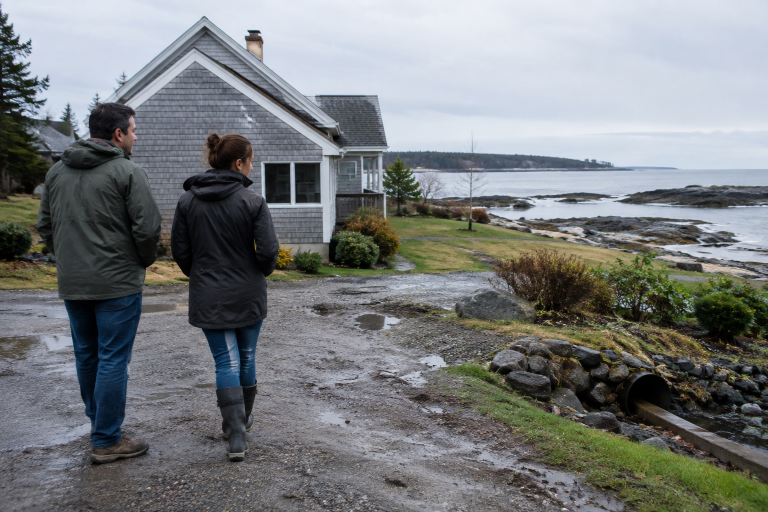
Flood risk is not limited to homes that sit directly at the water’s edge. Water can enter a property from coastal flooding, heavy rainfall, saturated ground, failing drainage, nearby streams, or runoff flowing toward the foundation. Review the property’s flood-zone designation, available elevation information, seller disclosures, and any evidence of prior water damage.
Use the FEMA Flood Map Service Center to review official flood hazard mapping for the address, then discuss what the map means with appropriate insurance, lending, and local professionals. Also, inspect gutters, downspouts, grading, culverts, retaining areas, basement walls, crawl spaces, and the driveway after rain when possible. Ask whether the access road or driveway has ever become difficult to use during storms.
Review Insurance Before Making an Offer
Request insurance quotes for the actual property early in the buying process. Standard homeowners’ insurance may not cover all water-related losses, and flood coverage is typically handled separately. Costs and eligibility can depend on factors such as the home’s location, elevation, roof condition, construction, prior claims, and exposure.
Ask the insurance professional to explain deductibles, exclusions, wind-related provisions, coverage limits, and any required repairs or inspections. If financing is involved, confirm that the available coverage meets lender requirements. A realistic insurance quote is more useful than a general online estimate because it reflects the house you are considering.
Inspect the Roof, Exterior, and Structure
A qualified inspector with coastal-property experience can help identify issues related to salt exposure and persistent moisture. A standard inspection is important, but buyers should ensure the review is detailed enough for the setting.
- Check roof age, flashing, gutters, roof penetrations, and water flow away from the house.
- Inspect windows, doors, seals, siding, trim, paint, decks, railings, and exterior stairs.
- Look for corrosion on fasteners, railings, electrical equipment, and HVAC components.
- Review foundation walls, basements, crawl spaces, and attic areas for staining, rot, mold, or moisture.
- Ask about repeated repairs, storm damage, and replacement history.
Evaluate Waterfront Features Separately
If the property includes direct water access, treat docks, piers, pilings, seawalls, bulkheads, lifts, and shoreline stairs as their own due diligence category. Their condition, legal status, and intended usefulness may differ from those of the home itself.
Confirm whether structures are permitted, shared, privately owned, or subject to easements and maintenance agreements. Look for cracking, settlement, leaning, washout, loose connections, and electrical concerns. A dock is only a benefit if it supports the buyer’s intended use, whether that means boating, swimming, kayaking, fishing, or simply enjoying an unobstructed shoreline.
Review Systems, Records, and Future Plans
Ask for records on the roof, heating system, electrical panel, septic system, well, water treatment equipment, additions, decks, garages, and previous shoreline work. Permits and maintenance documentation can help buyers understand what has been updated and what may need attention.
Buyers should also estimate recurring costs, including heating, snow removal, landscaping, exterior upkeep, private-road assessments, seasonal monitoring, and management for a second residence. Confirm whether short-term rentals, guest cottages, additions, new decks, docks, or major landscaping changes are allowed before treating those ideas as part of the purchase value.
A Simple Pre-Offer Checklist
- Review the exact site, nearby water features, road access, and neighborhood setting.
- Check flood mapping, elevation details, drainage patterns, and known water history.
- Obtain homeowners and flood-insurance quotes for the specific address.
- Schedule inspections for the home, major systems, septic, well, and waterfront features as applicable.
- Request permits, repair records, disclosures, and private-road or shared-access agreements.
- Confirm zoning, shoreland limits, rental rules, easements, and future-use restrictions.
- Compare annual maintenance demands with your budget, schedule, and intended lifestyle.
Questions Buyers Often Ask
Is a waterfront home always a better investment?
Waterfront appeal can be meaningful, but it does not eliminate the need to evaluate maintenance, insurance, access, shoreline condition, and future-use limits. The right choice depends on the buyer’s financial plan and intended use.
Should buyers avoid homes in flood zones?
A flood-zone designation is an important factor, not an automatic reason to reject a property. Review the actual location, elevation, insurance cost, past water history, construction features, and access conditions before deciding.
When should insurance be checked?
Insurance should be reviewed before an offer is submitted or well before inspection and financing deadlines expire. Coverage availability and cost can materially change the total cost of ownership.
Conclusion
A coastal home in the Bar Harbor area should offer more than a memorable view. It should also suit the buyer’s budget, maintenance capacity, daily needs, and long-term plans. By reviewing location, drainage, insurance, construction, shoreland rules, systems, and waterfront features early, buyers can make a more confident decision about a Maine coastal property in 2026.